
Transaction Highlights
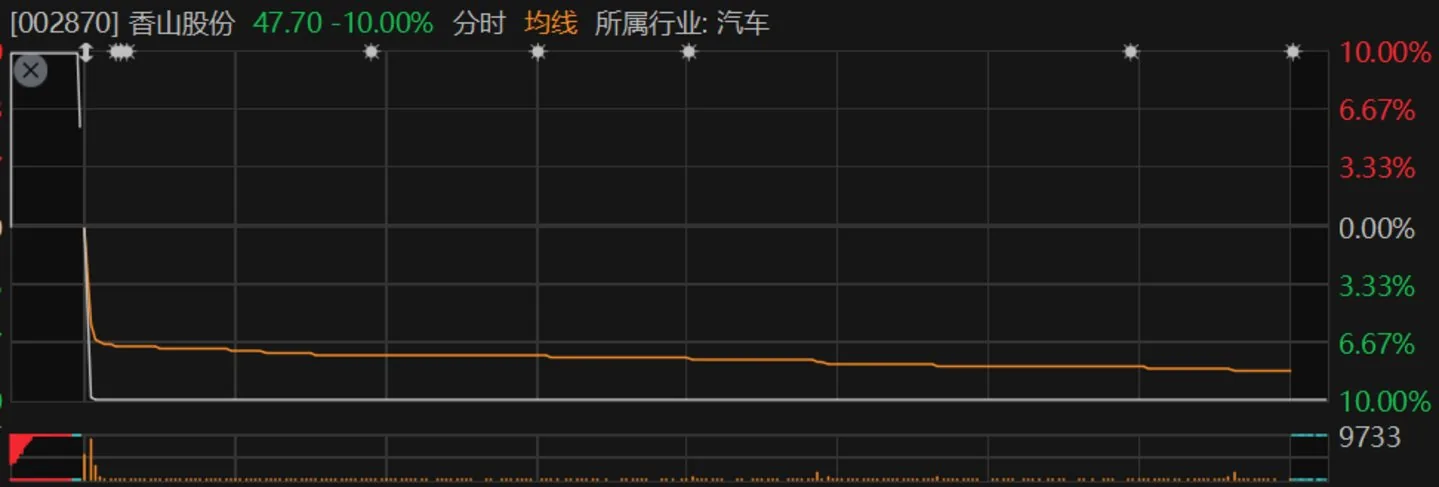
Xiangshan Shares (002870.SZ) disclosed its acquisition of 100% equity in Zhejiang Wuluo Wisdom City Technology Co., Ltd. on September 14, 2026, with a preliminary valuation of 800 million yuan. The transaction will be completed through a combination of cash and share issuance, while the stock plummeted to the daily limit down (47.70 yuan) upon resumption of trading on September 15.
- Deal Structure: 51% cash (approx. 408 million yuan), 49% share issuance at 35 yuan per share
- Performance Commitment: Compensation obligors promise cumulative non-net profit after non-recurring gains of at least 400 million yuan for 2027-2029, averaging 133 million yuan annually
- Timeline Note: Performance period skips 2026 entirely, focusing on next three years
- Market Reaction: Stock rose 35.69% in the 20 trading days prior to suspension, then dropped to limit down upon resumption, reflecting investor caution
Target’s Evolution and Business Shift
Wuluo Wisdom, though marketed as a key customer of Muxi Chip—“国产GPU四小龙之一” (one of China’s top four domestic GPU startups)—originally operated primarily as a trader. The company, founded in 2021, only entered the AI computing business in 2024, initially sourcing hardware from manufacturers, performing secondary testing and adaptation, then reselling without自有 production capacity.
The pivotal shift occurred in December 2025 with the completion of its Ningbo intelligent manufacturing base, enabling true self-developed production and transitioning from trader to hardware integrator and manufacturer.
Financial data shows extraordinary growth:
- 2024 revenue: 2.94 million yuan (loss-making)
- 2025 revenue: 36.66 million yuan, net profit: 19.07 million yuan
- H1 2026 revenue: 305 million yuan, net profit: 28.1 million yuan
The stark contrast: Revenue surged from under 50 million yuan annually to over 300 million in half a year within 18 months, yet performance remains highly dependent on upstream Muxi GPU chip supply and downstream intelligent computing center capital expenditure cycles. Its newfound production capacity and supply chain management need further validation at full-scale production levels.
Synergy Claims and Real Risks
Xiangshan’s acquisition rationale hinges on cross-industry synergies:
- Manufacturing Support: Its automotive precision manufacturing, supply chain management, and thermal management expertise can support Wuluo’s server production scale-up
- Technology Spillover: Wuluo’s liquid cooling and compute hardware technology may eventually apply to in-vehicle computing and new-energy storage
The preliminary plan explicitly warns: in-vehicle computing and data center servers operate under completely different customer certification and supply chain systems, meaning synergies remain a medium-to-long-term vision with little near-term order realization expected.
Core Business Strain Context
The cross-industry move reflects mounting pressure on Xiangshan’s core operations:
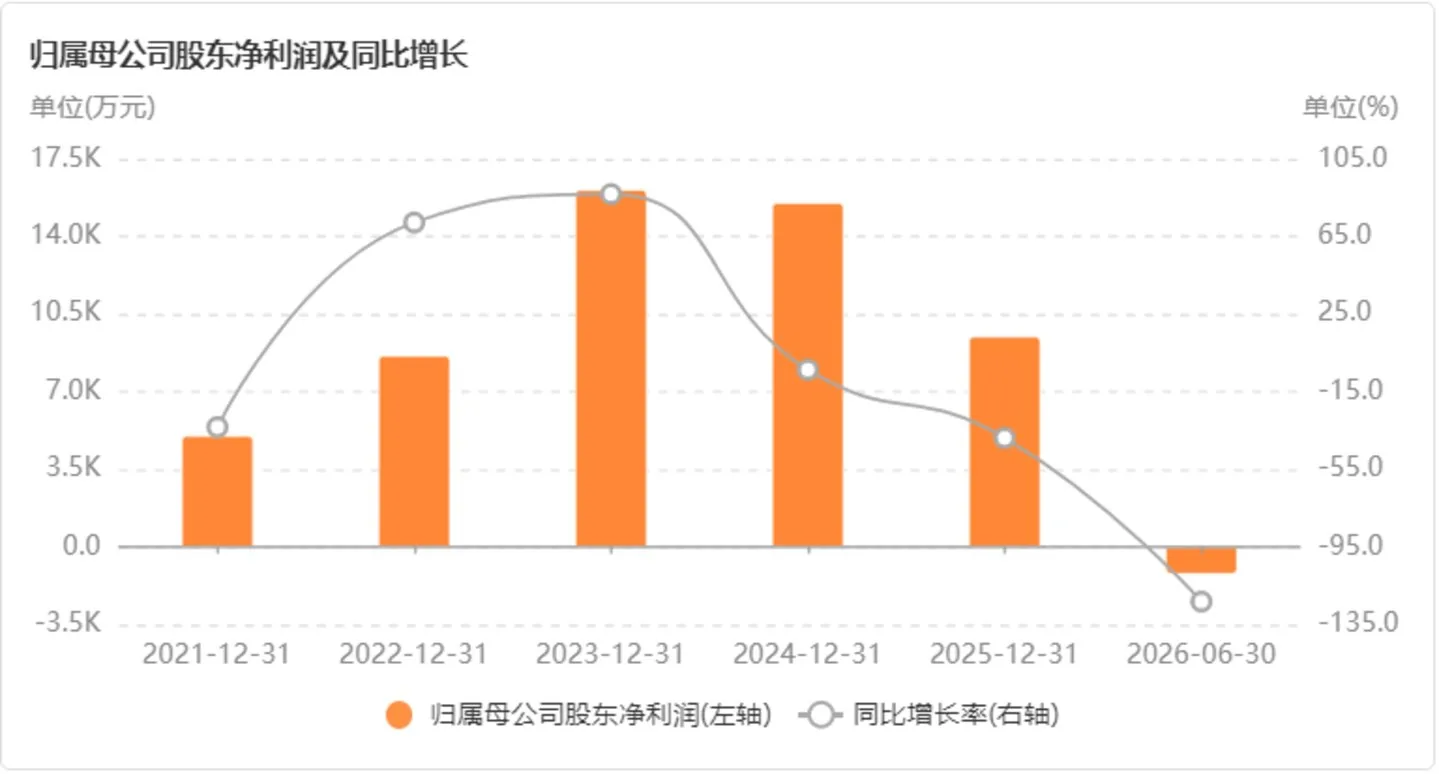
- H1 2026 revenue: 2.4 billion yuan (-18.23% YoY); net loss: 12.3 million yuan, switching from profit to loss
- Key subsidiary Junzheng Qunying affected by luxury vehicle market downturn; core air management business revenue fell 4.28% YoY
- New energy charging/distribution business grew 50.40% YoY but carries only 15.88% gross margin versus 23.33% for cabin components
- Huge foreign exchange losses: approx. 28 million yuan due to volatile exchange rates affecting euro/dollar-denominated overseas operations
- Disposal of weighing equipment business in late 2025 removed a stable profit buffer, concentrating earnings risk on the automotive component division
Investment Considerations
- Suitable for short-term traders: May benefit from AI computing sector sentiment, but high risk from potential performance commitment shortfalls
- Suitable for long-term investors to wait: Better entry point after 2026 annual report confirms core business stabilization and Wuluo’s full-year performance visibility improves
Final Thoughts
Cross-border acquisitions of AI computing assets reflect the broader anxiety among traditional manufacturers seeking second-growth curves. Whether Xiangshan can truly bridge the technological repurposing between automotive applications and data center infrastructure will determine if this bold bet becomes a strategic pivot or a new source of risk.